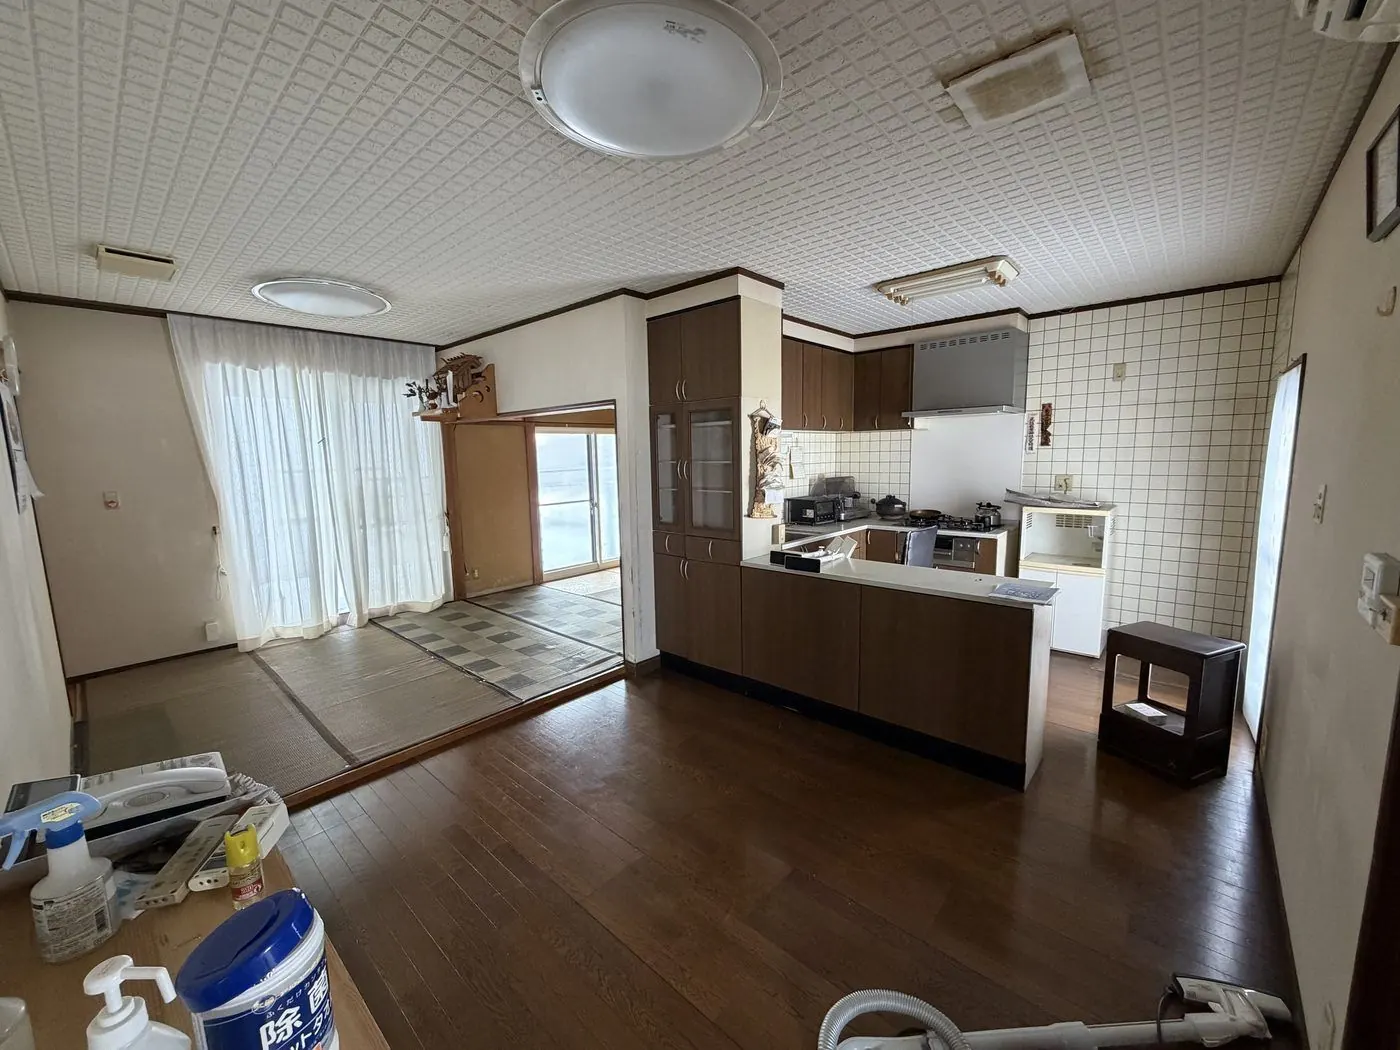
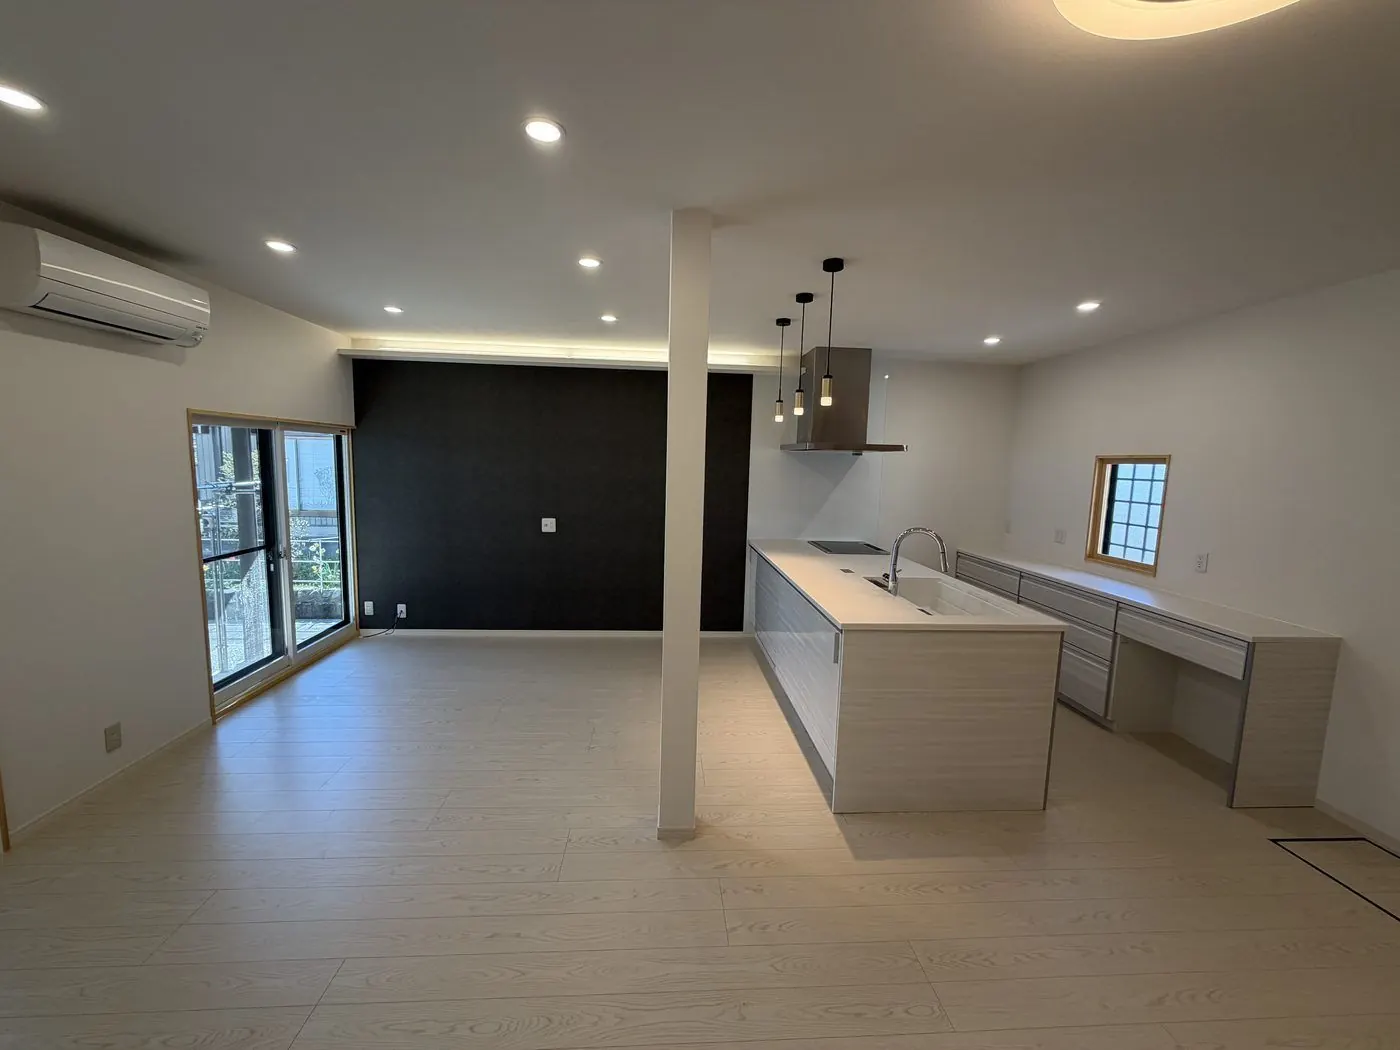
In a lease for company housing, we act as broker. When the company leases directly from the owner, we broker the lease between owner and company as a licensed real estate agent. Before the contract a licensed real estate transaction specialist explains the important matters, and the brokerage fee is capped by a notice of the Ministry of Land, Infrastructure, Transport and Tourism. The parties are the owner and the company; we are not a party.
Instead of leasing, the company can also buy the house and own it as company housing. That is a sale contract, and we take on the property search and the renovation.
A question we're often asked by someone in general affairs: if a company houses an employee in a house it has leased, does the company become a “sublease business”? No, it doesn't. A company may lease a house from a landlord and, under its own internal rules, let it to an employee as company housing. In that case the company doesn't count as a “sublease business” (an operator whose business is subletting). The Ministry of Land, Infrastructure, Transport and Tourism says so in its FAQ on the Rental Housing Management Business Act. It's the same when the company signs a lease with the employee and charges a fee below market rate. The company itself has no obligation under this Act to register or explain the important matters.
A provider that leases from the owner and sublets to the company, on the other hand, is what the same FAQ calls a "specified sublessor". In the contract with the owner it is bound by the ban on misleading advertising, the ban on improper solicitation, the pre-contract explanation of important matters and the delivery of the written contract. We do not work that way; we broker the lease between owner and company.
Lease or buy, the tax calculation when the company lets to employees is the same. The comparison of up-front cost, freedom to renovate and depreciation across the two forms is on Company housing and staff dormitories in Toyama (two forms).