Before you sell / tax on a vacant house

With the ¥30 million deduction, the tax is often zero.

The most powerful relief when selling an inherited home is the ¥30 million special deduction for vacant houses. Conditions, deadlines and pitfalls, as a checklist.

1 A rough figure from photos and an address. We work back from the deduction deadlineFree appraisal on LINE 2 9:00–17:00, Japanese only / after 17:00: Call us

Its formal name is the special deduction on capital gains from the sale of a deceased person's residence (a vacant house). When you sell an inherited family home, it lets you deduct up to ¥30 million from the profit on the sale. A family home in a rural area often sells for less than ¥30 million, in which case this deduction usually brings the capital gains tax down to zero. The conditions are detailed, though, so check on this page whether you qualify.

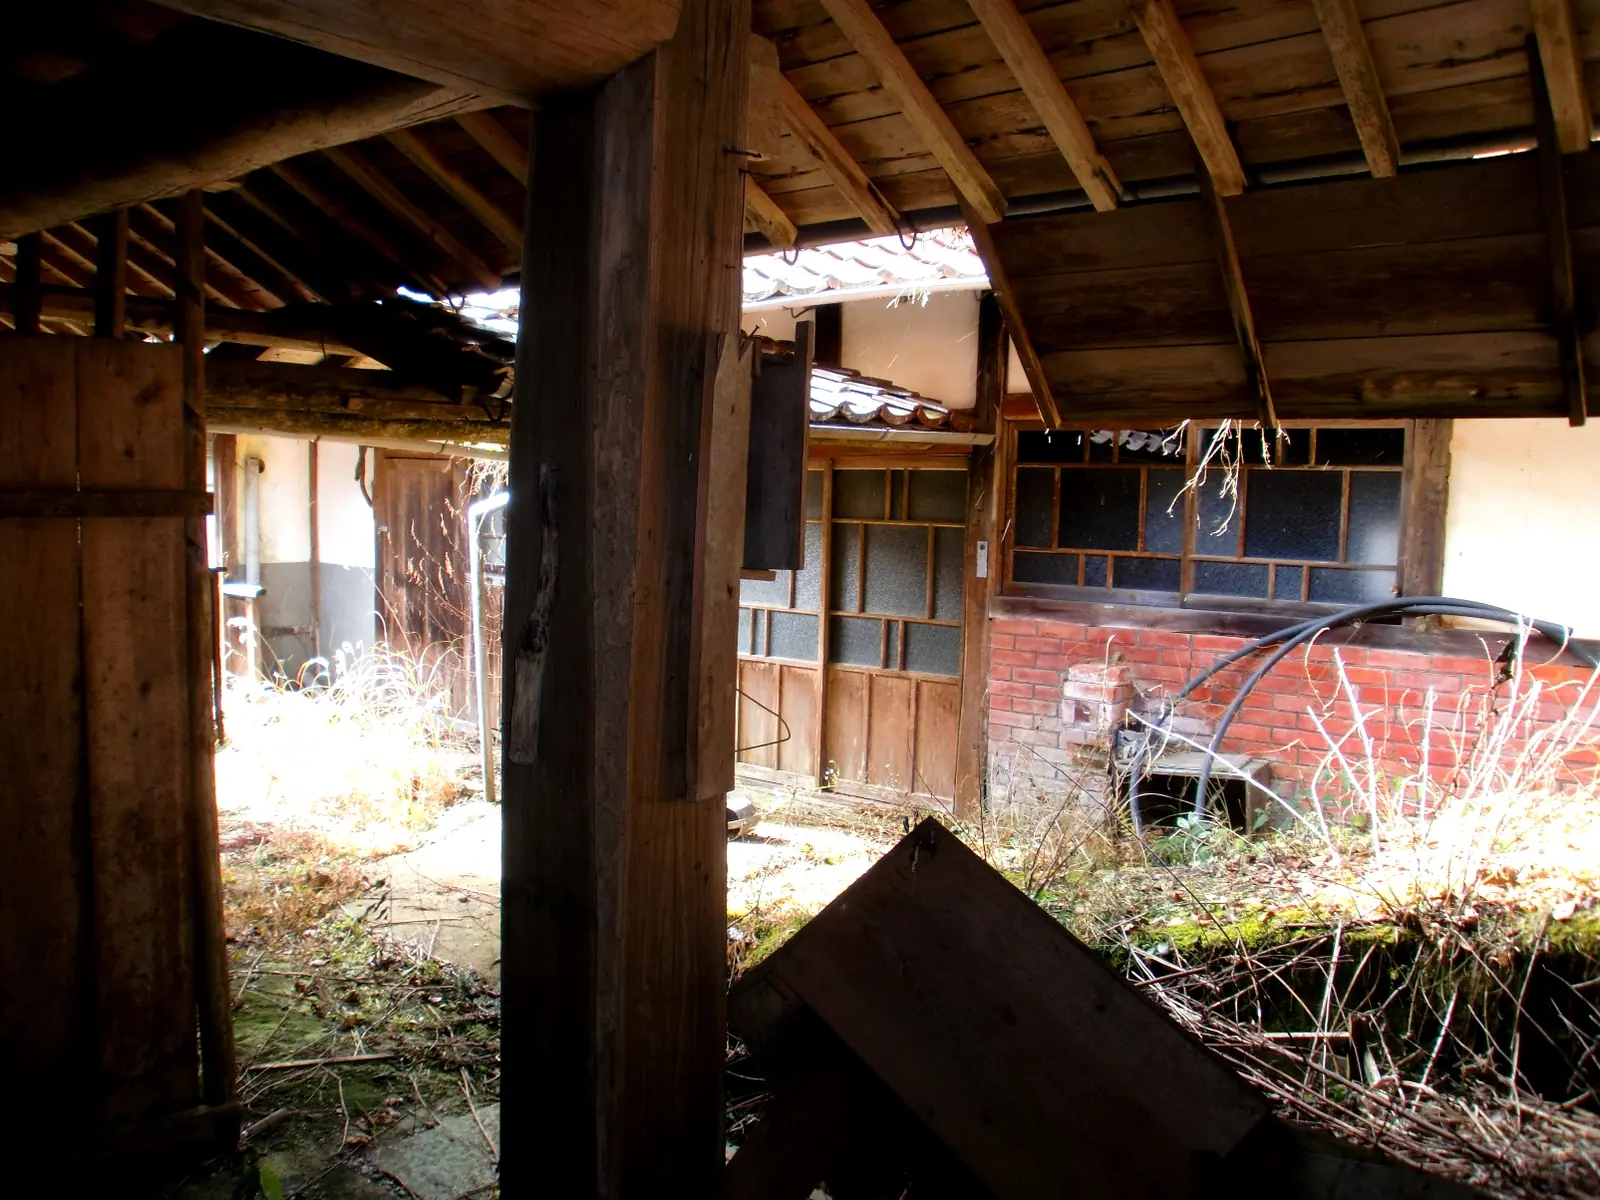
The eaves of a vacant houseThe eaves of a vacant house overgrown with weeds
Photo: warabi hatogaya "Komm süßer Tod - panoramio"(CC BY 3.0), cropped

Main conditions

  • The house was built on or before 31 May 1981 (condominium units excluded)
  • The deceased lived there alone until death (or in a care home, if conditions are met)
  • Between inheritance and sale it was not rented, lived in or used for business
  • Sale price ¥100 million or less
  • Sold by December 31 of the year in which three years have passed since the inheritance began, and in any case by December 31, 2027
  • If you sell the house standing, it must meet the national earthquake-resistance standard. But since 2024, it also qualifies if the buyer demolishes it or carries out seismic reinforcement by 15 February of the year after the sale

Up to ¥30 million per person. For sales from 2024, with three or more heirs it drops to ¥20 million each.

How much difference: an example

Sold for ¥12 million, acquisition cost unknown (deemed 5%) No deduction Tax about ¥2.3 million With the ¥30 million deduction Tax ¥0
  • Sold for ¥12 million, cost unknown (deemed 5% = ¥600,000), no deductionTax about ¥2.3 million
  • Same sale with the ¥30 million deductionTax ¥0

In the usual Toyama range (a few million to twenty-odd million yen), whether the deduction applies changes what you keep by hundreds of thousands to millions of yen. Well worth checking before you decide how to sell.

Where it trips up

  • Renting it out before the sale, even briefly, disqualifies it — minpaku and monthly lets included
  • If you paid inheritance tax, it is a choice against the acquisition-cost addition; which is better depends on the tax paid
  • You need a certificate from the municipality confirming the deceased's residence, and a tax return
  • Documents proving the house was vacant — electricity and gas disconnection certificates — take time to gather

The deduction applies to a sale to us too

There's a common misunderstanding that selling to a business buyer rules out the deduction. Who the buyer is has nothing to do with eligibility. If the conditions are met, it applies to our direct purchase too. Since 2024, it also applies when the buyer demolishes the house or carries out seismic reinforcement after buying. That means you can sell the house as it is, and we, the buyer, can handle the demolition — you don't have to pay the demolition cost yourself first. See also our guide to selling an inherited vacant house for the full process.

FAQ

The house is newer than 1981. Is there any relief I can use?+−

Not the vacant-house deduction, but depending on the sale, other rules such as the acquisition-cost addition (if you paid inheritance tax) may apply. And tax is on the gain, so if the acquisition cost is known the tax itself may be small. Confirm with the tax office or a tax adviser.

My parent died while in a care home. Does it qualify?+−

That the owner needed nursing care and moved into a care home. That after moving in, the house was still used to store belongings and so on, and was not rented out to anyone. Meeting these conditions makes it eligible. If this looks like your case, gathering documents early — the utility shut-off certificate, the care home admission record — makes things go smoothly.

Where do I get the certificate?+−

Apply to the relevant division of the municipality where the house is (vacant-house measures, or building and housing). Allow one to two weeks. If we buy the house, we help organise the documents.

If I sell a vacant house cheaply, can I use Toyama City's incentive?+−

Toyama City has a Vacant House Circulation Incentive. It applies when you sell an inherited vacant house on or after 1 April 2026, receive the Confirmation for the Deceased's Residence (the document also used to claim the ¥30 million special deduction) from the Mayor of Toyama, and the sale price is ¥8 million or less. Apply within three months of the confirmation being issued. Check the amount and the latest conditions on Toyama City's page.

This page is a general explanation. Whether a tax rule applies, and the amounts, depend on your situation; confirm with the tax office or a tax adviser. The rules are as of August 2026.

We do the paperwork with you

Before deciding whether to sell, just know the price.

Appraisal is free, with no charge if you decline. The contents can stay.

Request a free appraisal Selling a vacant house or kominka in Toyama → Message us on LINE

The whole process is here.

The order from registration to handover, and a guide for the undecided.

Selling an inherited house → What to do with the family home →

Written by Kota Makimura, Hokuriku Homes Updated

Phone9:00–17:00 LINEAppraisal from photos Free appraisalTakes 1 minute
LINEChat